
What do you think?
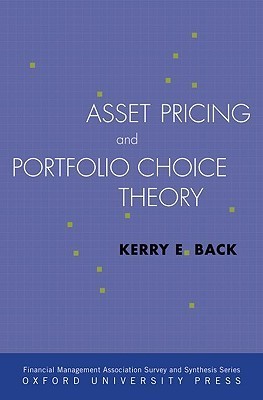
Asset Pricing and Portfolio Choice Theory
In Asset Pricing and Portfolio Choice Theory , Kerry E. Back at last offers what is at once a welcoming introduction to and a comprehensive overview of asset pricing. Useful as a textbook for graduate students in finance, with extensive exercises and a solutions manual available for professors, the book will also serve as an essential reference for scholars and professionals, as it includes detailed proofs and calculations as section appendices.
Topics covered include the classical results on single-period, discrete-time, and continuous-time models, as well as various proposed explanations for the equity premium and risk-free rate puzzles and chapters on heterogeneous beliefs, asymmetric information, non-expected utility preferences, and production models. The book includes numerous exercises designed to provide practice with the concepts and to introduce additional results. Each chapter concludes with a notes and references section that supplies pathways to additional developments in the field.
Topics covered include the classical results on single-period, discrete-time, and continuous-time models, as well as various proposed explanations for the equity premium and risk-free rate puzzles and chapters on heterogeneous beliefs, asymmetric information, non-expected utility preferences, and production models. The book includes numerous exercises designed to provide practice with the concepts and to introduce additional results. Each chapter concludes with a notes and references section that supplies pathways to additional developments in the field.
504 pages, Hardcover
First published January 1, 2010
Ratings & Reviews
Friends & Following
Create a free account to discover what your friends think of this book!
Community Reviews
Displaying 1 - 1 of 1 review
November 10, 2024
A fundamental book for anyone doing quantitative research, introducing asset pricing theories that starts off with discrete followed by stochastic settings. Basics of portfolio selection, investor utility and classical factor model literature are covered here. Good to have postgraduate level of mathematics knowledge for a comfortable read.
Displaying 1 - 1 of 1 review